What Does It Mean for a Business to Be Exit-Ready?
What if a strong sign of exit readiness is that your business can keep performing without you at the center of every decision? The question “what does it mean for a business to be exit-ready” is not simply whether you’re prepared to sell. It’s whether the company’s financial picture is clear, key relationships and knowledge are supported across the team, and operations can continue through a future transition.
It’s understandable to associate exit planning with an imminent sale. But readiness is better treated as an ongoing operating discipline that can support an internal transition, an external sale, or stronger decisions today. You don’t have to choose a path before you’re ready.
This article explains exit readiness in plain language, highlights practical signs that financial visibility or owner independence may be limited, and offers a clear place to begin. Better financial clarity and reduced owner dependency can strengthen transferability over time, while connecting day-to-day decisions to the long-term health of the enterprise.
Key Takeaways
- Understand what it means for a business to be exit-ready: the company can transition without relying entirely on its owner, while keeping future paths open.
- Assess whether financial information is timely and useful enough to guide decisions, not simply record past performance.
- Look beyond profitability for evidence of transferability, including how much critical knowledge and authority depends on the owner.
- Start with a manageable sequence: clarify your goals, establish a baseline, prioritize gaps, and revisit progress.
- Evaluate financial decisions through both their profit and cash impact and their enterprise-value impact.
What Does It Mean for a Business to Be Exit-Ready?
An exit-ready business can continue operating and transition leadership or ownership without relying entirely on its owner. That takes more than a strong financial result. Critical knowledge, customer relationships, decision-making authority, and operating routines need to be understood and supported across the organization, rather than held by one person alone.
Exit readiness is a business capability, not a date on the owner’s calendar. It creates options; it doesn’t mean a sale is imminent or inevitable. That distinction matters when 80 to 90 % of an owner’s net worth sits inside the business. A company that can function beyond its founder is better positioned to maintain continuity through change, whatever the owner ultimately decides.
Exit readiness is broader than preparing for a sale
An exit strategy describes possible ways an owner may leave or transfer a business. The broader Exit strategy concept includes different routes and purposes, but readiness is about the company’s underlying ability to support a transition. Timing and route are separate decisions.
Readiness can support continuity while ownership remains unchanged, too. If a key customer issue or operational decision always requires the owner, the company may struggle to maintain momentum during an unexpected absence or leadership change. Clear responsibilities, accessible operating knowledge, and appropriately distributed decision authority can reduce that dependence. No single transition route is right for every owner; stronger transferability helps preserve choice.
Why readiness matters before a transition is certain
Starting before a transition is certain gives an owner room to understand what already works and where the business depends too heavily on individual knowledge or authority. That clarity can guide practical improvements over time, rather than concentrating all the work around a deadline. It also helps distinguish durable strengths from activities that appear stable only because the owner personally keeps them moving.
Transferability matters in ordinary operating conditions. A company with documented processes and capable decision-makers may be better able to handle routine disruptions, delegate work, and maintain consistency as responsibilities evolve. These qualities support resilience now, not only during a future handoff.
For a deeper look at building an enterprise that can carry its purpose forward, see Exit Planning for Business Owners: The Master Craftsman’s Guide to Transferable Legacy. The central question is practical: could the business preserve its performance and relationships if the owner stepped back from daily decisions? The answer can reveal where to focus without requiring an immediate transition plan. The scope of each engagement is defined in the client’s written agreement.
The Building Blocks of an Exit-Ready Business: Financial Clarity and Transferability
Financial clarity and transferability reinforce each other. Reliable, timely information helps an owner understand how the business is performing and what choices may mean for cash and profit. Documented processes and clear decision rights help ensure that performance doesn’t depend on the owner personally interpreting every number or directing every action.
Three weeks late is how old the average owner’s financial picture is when the decision has to be made. If information arrives after an important choice, it may describe what has already happened without helping the owner weigh what to do next. A practical answer to what does it mean for a business to be exit-ready starts with information that is consistent enough to guide decisions and accessible to the people responsible for acting on them.
Financial visibility that supports forward-looking decisions
Useful financial visibility brings together performance, cash, and a focused set of indicators that reflect how the business operates. An owner might review revenue alongside margins, cash availability, and changes in customer demand. The purpose isn’t to collect more figures for their own sake. It’s to understand what is changing, what may require attention, and how a decision could affect the company beyond the current reporting period.
Consider a proposed hire or equipment purchase. Recent profit alone may not show when cash will be needed or whether the choice supports the company’s longer-term strength. Timely information creates a clearer basis for weighing trade-offs. Financial decision support can inform business planning; accounting, legal, tax, and investment matters remain outside the scope of this general discussion.
Operations that can function beyond the owner
A transferable operation makes essential work understandable and repeatable. Document the steps that materially affect service, quality, or cash flow, and clarify decision rights: who handles a routine issue, who can approve an exception, and when an issue needs to be escalated. The goal isn’t to record every detail. It’s to make critical work less dependent on one person’s memory or availability.
Concentrated knowledge creates continuity risk. If only the owner knows how a key customer relationship is managed, how a recurring problem is resolved, or why a process has an important exception, others may struggle to maintain the same standard. A useful test is whether a capable team member can find the relevant information, understand their authority, and complete the work without waiting for the owner to provide missing context.
Financial visibility helps identify where performance depends on particular decisions; documented operations help others carry those decisions out. A transferable company can explain how it performs without relying on its owner’s memory. For practical guidance on recording repeatable work, see What Is an SOP in Business? The Blueprint for a Transferable Legacy. Owners seeking a structured view of financial clarity and transferability can explore 41 Legacy’s strategic finance approach.
Is a Profitable Business Automatically Exit-Ready? Evidence Versus Assumptions
No. Profit is an important measure of performance, but it doesn’t establish that the business can operate or maintain its results without the owner. The question “what does it mean for a business to be exit-ready” calls for evidence across the company, not confidence in a single figure. Inconsistent financial information, undocumented work, or decisions that routinely wait for the owner can make a profitable company difficult to understand and transfer.
What a strong profit figure can, and cannot, tell you
A profit figure can show that the business generated earnings over a given period. On its own, it doesn’t explain how repeatable those results are, how clearly they’re understood, or whether the company can sustain performance if the owner steps away from daily decisions. To interpret profitability, consider the quality and consistency of the information behind it, and how much the result depends on one person.
Compare assumptions with observable evidence:
| Owner assumption | Evidence to look for |
|---|---|
| “We’re profitable, so performance is clear.” | Financial information is consistent over time, and leaders can explain the main changes in results. |
| “The team knows how to do the work.” | Important processes are documented and followed consistently, including how exceptions are handled. |
| “There are capable people who can step up.” | Leaders can describe their responsibilities, make decisions within clear boundaries, and carry work forward. |
| “The business can run without me.” | Routine decisions and key relationships continue without constant owner intervention. |
Readiness signals owners can observe
Test the evidence in ordinary operations. Ask a leader to explain a change in performance, describe the next steps, and identify which decisions they can make independently. Review whether essential processes are written down and used in practice, not merely stored in a document. Note where work pauses until the owner supplies context or approval. These observations reveal specific gaps to address.
Separate what can be verified from what is hoped for. Confidence in the team may be well founded, but it becomes stronger evidence when responsibilities are clear and people demonstrate that they can carry them out. Informal assurances matter less than consistent practice: a process followed across the team, a decision made within agreed authority, or a result explained using shared information.
This is a diagnostic, not a pass-or-fail score. A gap in one area doesn’t determine the company’s future; it identifies a question worth examining. Record what evidence exists, where it comes from, and what remains dependent on the owner. Distinguishing belief from demonstration gives the next readiness discussion a more reliable starting point.
How to Start Building Exit Readiness Without Disrupting the Business
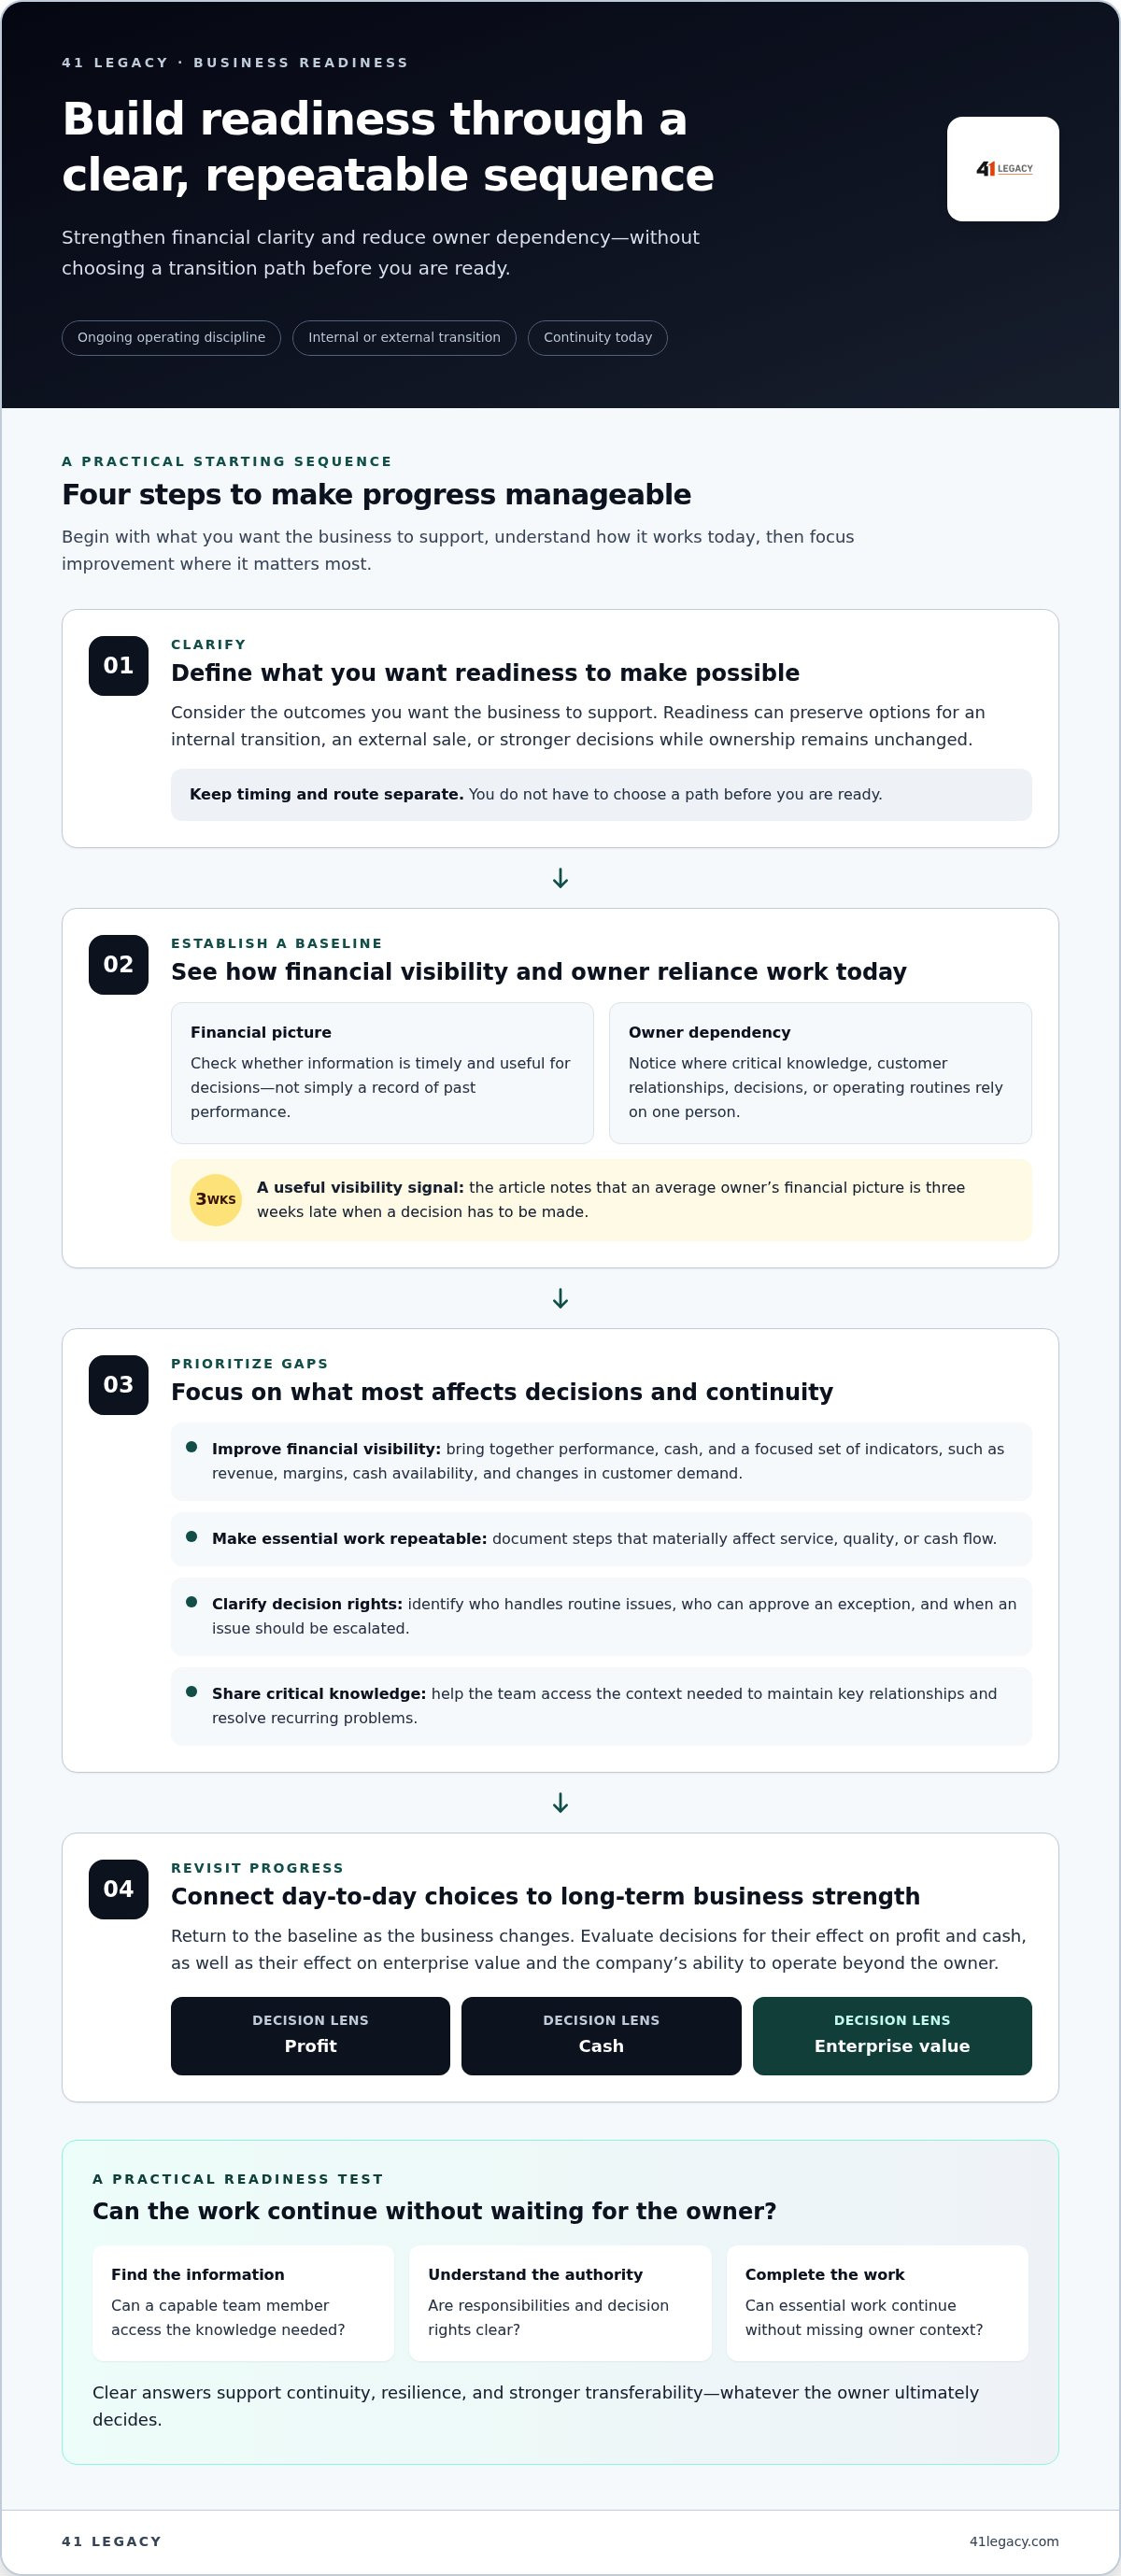
Readiness work can begin alongside normal operations. The useful first question is not how quickly a transition could happen, but what the owner wants the business to support and what would make it more transferable. A practical sequence keeps the work focused:
- Clarify your goals. Consider what you want the business and your role to look like over time. You don’t need to choose a transition route or set a sale date to identify what matters to you.
- Establish a baseline. Gather the information you already use to understand performance, cash, key business indicators, responsibilities, and owner-dependent decisions. Mark each item as a known fact, an estimate, or an unanswered question.
- Prioritize the gaps. Start with information needed for near-term decisions and activities that routinely stall without the owner. Choose a small number of improvements that fit within the company’s existing capacity.
- Revisit progress. Review the selected information and responsibilities on a recurring basis. Note what has changed, what remains unclear, and whether priorities still fit the owner’s goals and operating needs.
Create a clear baseline before choosing priorities
A baseline is a grounded picture, not a polished presentation. Separate what the records show from what the team estimates, and capture questions that still need an answer. Then consider both the owner’s transition horizon and the demands of current operations. An owner thinking about a future handoff may focus on different gaps than one seeking to reduce day-to-day dependence while remaining in the business.
This is also a useful point to coordinate existing professional advisors around shared business priorities. The owner can identify the operating or financial questions that need attention, clarify who is addressing each one, and keep discussions connected to the company’s goals. Each advisor can contribute within their own professional role; this is general information, not legal, tax, investment, or advice for a specific business. For a related discussion of value-building priorities, see How to Increase Enterprise Value: A Comprehensive Guide for Business Owners.
Turn readiness priorities into an operating rhythm
A short roadmap is easier to act on than a long, unsequenced task list. For each priority, define the next practical step, who owns it, and what observable change would show progress. For example, a priority might be to make a recurring decision less dependent on the owner; progress could mean that a designated leader understands the decision boundary and can explain how it was applied.
Review a limited set of indicators and responsibilities at a cadence that suits the business. Keep the review focused: what do the current facts show, where is judgment still required, and what is the next priority? This helps maintain momentum without turning readiness into a separate project that competes with operations. To bring financial clarity and transferability into a structured plan, explore 41 Legacy’s strategic advisory support.
How 41 Legacy Supports Financial Clarity and Exit Readiness
For owner-operated companies with $1 M to $30 M in annual revenue, 41 Legacy connects financial clarity with work to strengthen transferability. The starting point is a fixed, six-week financial clarity intensive with one working session per week. It provides weekly deliverables and a custom KPI tracking sheet, helping clarify the company’s financial picture and identify top profit levers before ongoing work begins.
The Enterprise Value Lens is part of every recommendation. Each financial decision is evaluated through both its profit and cash impact and its enterprise-value impact. This dual-lens evaluation helps owners consider not only whether a decision supports current performance, but also how it relates to the long-term strength and transferability of the business. It supports clearer decisions, without promising a particular result.
What the fixed, six-week financial clarity intensive establishes
The intensive includes one working session per week, weekly deliverables, and a custom KPI tracking sheet. Weeks 1 and 6 are identical for every client; weeks 2-5 are customized after week 1. The week 3 deliverable is a 13-week cash-flow forecast.
This defined process offers a focused period to examine the financial picture without treating readiness as a last-minute transaction project. The findings can help an owner identify which information is most useful for decisions and where further attention may support clearer financial management.
How the CFO Seat fits into the readiness picture
After the intensive, the ongoing CFO Seat provides a monthly strategic finance rhythm. Its focus includes budgeting, forecasting, KPI review, decision support, working-capital discipline, and enterprise-value tracking. Every recommendation is evaluated through both its profit and cash impact and its enterprise-value impact. This forward-looking support gives the owner a continuing structure for considering financial choices and their implications for the business.
The work can also coordinate with the owner’s existing professional advisors around shared business priorities. Strategic finance can help clarify the business questions and financial context for broader discussions, while each advisor continues in their own professional role. The aim is a more coherent view of the company, not a replacement for the people already supporting it.
For an owner considering a clearer financial baseline and stronger transferability, a 30-minute conversation is a measured place to begin. Start a 30-minute conversation. No pitch. No pressure.
Build the Next Layer of Independence
The question, what does it mean for a business to be exit-ready, becomes more useful when it leads to a practical next step: identify one decision, relationship, or responsibility that still depends too heavily on you. Then consider what would allow the business to handle it with greater clarity and continuity. That work can begin well before you decide whether, when, or how to transition.
Readiness develops through deliberate choices that help the company function as a durable asset, not simply as an extension of its owner. You don’t need to resolve every future possibility today. Start by identifying what you want the business to support and which questions deserve attention first.
Start a 30-minute conversation with 41 Legacy. No pitch. No pressure.
Frequently Asked Questions
Can a profitable business still have exit-readiness gaps?
Yes. Profit confirms that a business generated earnings over a period, but it doesn’t show whether those earnings are consistent, clearly explained, or reliant on unusual owner effort. If a major customer relationship or delivery decision is managed only by the owner, current profit may not reveal how performance would hold up when that person is unavailable. Compare results across periods and identify the operating factors that produced them.
How often should an owner revisit business exit readiness?
Revisit readiness on a recurring cadence that fits the pace of decisions and operating changes, rather than waiting until a transition is near. A review can be prompted by a leadership change, a new growth initiative, a shift in customer concentration, or a major investment decision. Use each check-in to confirm what has changed, which dependencies remain, and whether the next priority still aligns with the owner’s goals.
What happens if a business depends heavily on its owner?
Decisions may queue up, relationships can become difficult to hand off, and employees may lack authority to resolve routine issues. The immediate concern is continuity: work can slow or become inconsistent when the owner is unavailable. Map recurring decisions and identify who could make them, what information they’d need, and where a clear decision boundary or process would help the business keep moving.
Does exit readiness matter if the owner is not planning a transition soon?
Yes. Even without an imminent transition, it’s useful to ask: what does it mean for a business to be exit-ready in the context of your current goals? It means building the company’s capacity to operate with less dependence on one person. That can give the owner more flexibility in daily responsibilities and help the business respond to changes without turning every decision into a personal bottleneck.
Can a company work on growth and transferability at the same time?
Yes. Growth efforts can also strengthen transferability when they build repeatable capabilities rather than adding work that only the owner can manage. For example, a company expanding its service offering might define who handles delivery decisions and how performance will be reviewed. Consider each initiative through both its immediate operating demands and its effect on the company’s ability to function beyond the owner.
What does a 13-week cash-flow forecast help an owner understand?
A cash-flow forecast helps an owner see the expected timing of money coming into and going out of the business. That view can highlight periods when planned obligations may outpace anticipated receipts, creating an opportunity to examine assumptions and consider the timing of decisions. It can also support discussions about working-capital needs. A forecast is a planning tool, not a guarantee that actual cash flows will match expectations.
Article by
Mike Laskowski
Mike Laskowski is a Business Value Growth Strategist who helps business owners uncover the truths that drive their performance, risk, and readiness. Blending forensic interviewing from a 26‑year federal career with Strategic Capacity analysis and CEPA methodology, he works upstream to reduce owner dependency, increase transferability, and strengthen enterprise value. Mike guides founders through clarity, operational evolution, and transition readiness so their companies become transferable, owner‑independent assets that endure beyond the founder.
Disclaimer
This article is for educational and informational purposes only and does not provide legal, tax, investment, or business brokerage advice. 41 Legacy does not offer M&A brokerage services, legal document drafting, tax preparation, or investment advisory services. Business owners should consult licensed professionals in those disciplines before making decisions related to business transactions, legal matters, tax strategy, or financial planning. All examples are illustrative and may not apply to your specific situation.